

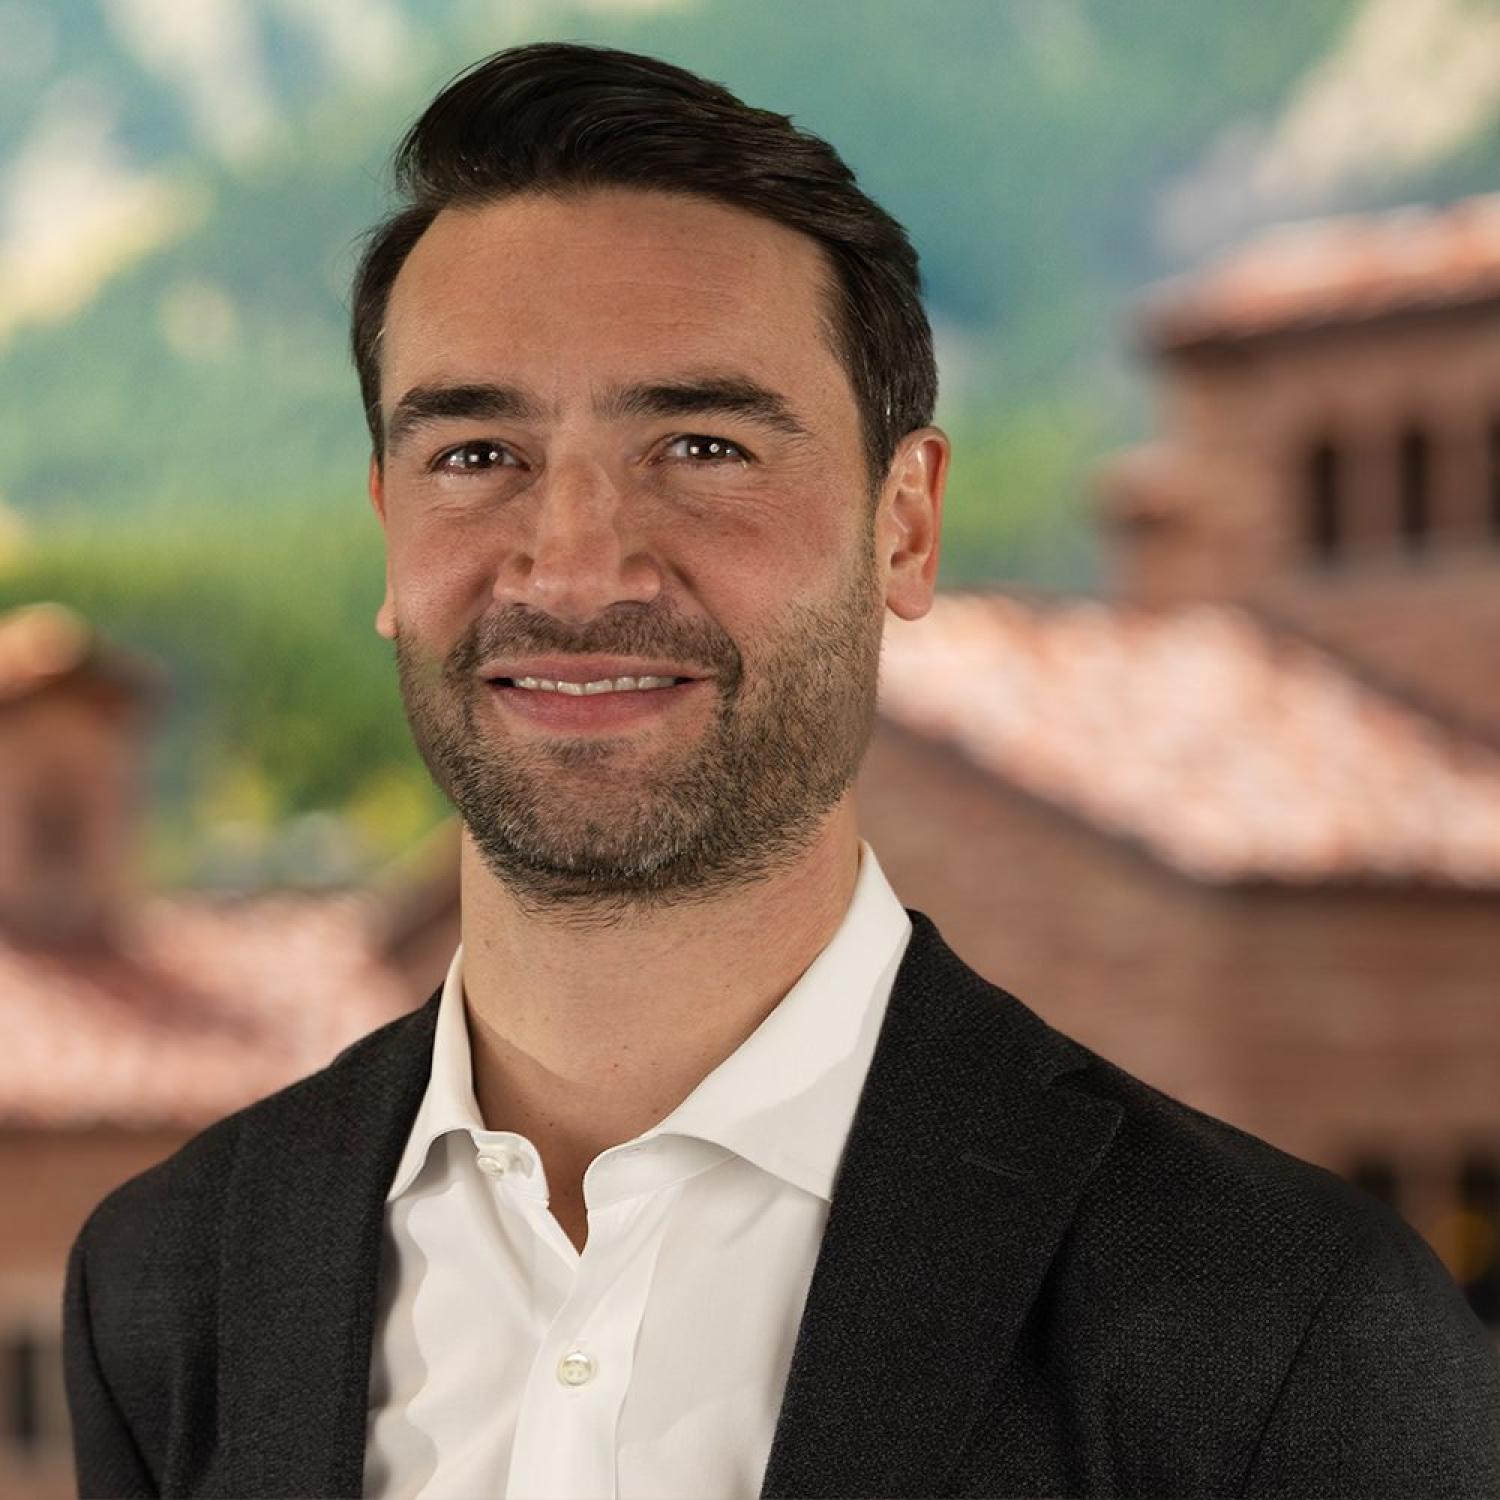
Andrea Buffa
- Stone Family Faculty Scholar
- Assistant Professor
- FINANCE
Education
PhD, Finance, London Business School, 2012
MRes, Finance, London Business School, 2008
MSc, Finance and Economics, London School of Economics, 2007
MSc, Economics, Collegio Carlo Alberto, 2005
BA, Economics, University of Turin, 2004
Biography
Andrea Buffa's research interests include asset pricing, institutional asset management, financial institutions, ESG investing, contract theory and information economics. His work on the impact of asset management contracts on asset prices has received the attention of The Economist,Financial Times and Bloomberg Businessweek. His work on ESG funds has been featured on several online media outlets.
Buffa is the recipient of several awards, including the 2013 Best Young Researcher Award by the Multinational Finance Society, the 2015 SFS Cavalcade Award for the Best Paper in Asset Pricing by the Society for Financial Studies, the 2024 Best Paper Award in Investments by the Financial Management Association, the 2024 KRX Best Paper Award by the Asia-Pacific Association of Derivatives, and the 2025 Best Paper Award at Spring Finance Workshop, which was organized by the University of Luxembourg and McGill University.
Before joining the University of Colorado Boulder, he was an assistant professor of finance at Boston University.
Research
Research Areas of Interest
- Asset pricing
- Instiutional asset management
- ESG investing
- Contract theory
- Information economics
Selected Publications
- Buffa, Andrea M., Qing Liu, and Lucy White. 2025. Privacy and Team Incentives. The Journal of Finance, 80(6), 3443- 3497.
- Buffa, Andrea M. and Idan Hodor. 2023. Institutional Investors, Heterogeneous Benchmarks and the Comovement of Asset Prices. Journal of Financial Economics, 147(2), 352-381.
- Buffa, Andrea M., Dimitri Vayanos, and Paul Woolley. 2022. Asset Management Contracts and Equilibrium Prices. Journal of Political Economy, 130(12), 3146- 3201.
- Buffa, Andrea M. and Giovanna Nicodano. 2008. Should Insider Trading be Prohibited when Share Repurchases are Allowed?. Review of Finance, 12(4), 735-765.
- Buffa, Andrea M. 2004. Strategic Insider Trading with Imperfect Information: A Trading Volume Analysis. Rivista di Politica Economica, 94(6), 101-143.
Working Papers
- Abis, Simona, Andrea M. Buffa, and Meha Sadasivam. 2025. Different Shades of ESG Funds.
- Atmaz, Adem and Andrea M. Buffa. 2025. Volatility Disagreement and Asset Prices.
- Abis, Simona, Andrea M. Buffa, Apoorva Javadekar, and Anton Lines. 2022. Learning from Prospectuses.
- Buffa, Andrea M. and Apoorva Javadekar. 2022. A Signaling Theory of Mutual Fund Activeness.
- Buffa, Andrea M. and Apoorva Javadekar. 2022. Decomposing Fund Activeness.
- Basak, Suleyman and Andrea M. Buffa. 2019. A Theory of Model Sophistication and Operational Risk.
- Buffa, Andrea M. 2014. Systemic Risk Management.
- Buffa, Andrea M. 2014. Insider Trade Disclosure, Market Efficiency, and Liquidity.
Teaching
Buffa teaches courses in financial derivatives, corporate finance, and the theory of asset pricing across undergraduate and doctoral programs.
Media, Insights & News
- Double agents: The way investors choose fund managers may cause anomalies in the markets. The Economist (2014).
- Risk-return relationship has been upended. Financial Times (2014).
- One of the Most Famous Rules of Investing Might Be Totally Wrong. Bloomberg Businessweek (2014).
- ESG investing: Are your values truly reflected in your portfolio? CU Boulder Today (2024).
- Only 20% of ESG funds meet the criteria for ‘impact’ investments. ESG Post (2024).